 The New Experience Newspapers Online News Indepth, Analysis and More
Tax The Few, Not The Many: FG Outlines Philosophy Behind New Tax Regime
By Prince Benson Davies????
The Federal Government has said its new tax policy is structured to promote prosperity rather than poverty, with emphasis on enabling businesses to grow, attract investment and create jobs as a pathway to achieving a one trillion dollar economy by 2030.
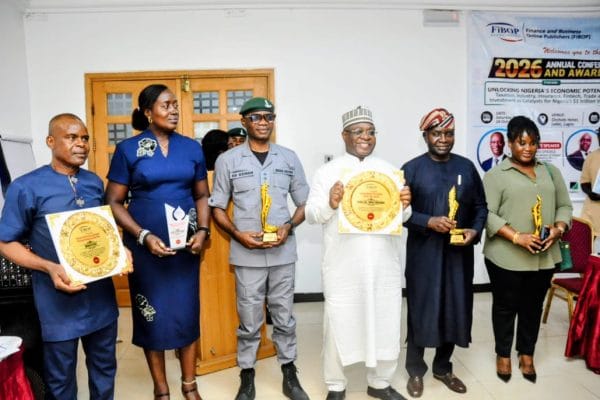
The Chairman of the Presidential Committee on Fiscal Policy and Tax Reforms, Mr. Taiwo Oyedele, who is also the Coordinating Minister of the Economy, stated this at the 2026 Finance and Business Online Publishers Association, FiBOP, Conference and Awards held in Lagos.
Mr. Oyedele, who was represented by his Special Adviser on Revenue, Mr. Olufemi Olarinde, said the success of the one trillion dollar economy agenda would not be determined by how much revenue government collects, but by how effectively its fiscal policies support enterprise growth and improve living standards.
He explained that the new tax reform is anchored on a simple philosophy of taxing prosperity and not poverty, and ensuring that the burden does not fall disproportionately on ordinary citizens.
According to him, the principle is captured in the phrase, Tax prosperity, not poverty. Tax the few and not the citizens.
Mr. Oyedele noted that the shift represents a departure from a narrow focus on revenue collection to a broader objective of building an economy that generates sustainable wealth and expands opportunities for Nigerians.
Speaking on the theme, The New Tax Policy and Its Role in Accelerating the $1 Trillion Economy Target by 2030, he argued that the country’s economic progress should be measured beyond Gross Domestic Product figures.
He said the real indicators for Nigerians would be whether businesses are expanding, household incomes are rising, jobs are becoming more accessible and living conditions are improving.
The minister stressed that the government recognises the link between business survival and economic growth, noting that an entrepreneur who receives the right support today has the potential to become a major employer in the near future.
He cautioned that a tax system that imposes unnecessary burdens on businesses could stifle growth and ultimately shrink the revenue base it seeks to expand.
He disclosed that government is working to ensure better coordination between monetary policy and tax administration, including aligning tax-related interest and penalty rates with prevailing monetary conditions while maintaining appropriate sanctions for non-compliance.
The objective, he said, is to reduce excessive costs on businesses, improve access to capital and create incentives for investment, business expansion and job creation.
Mr. Oyedele however pointed out that tax reforms alone cannot deliver the one trillion dollar economy target without complementary growth in productive sectors.
He said Nigeria must strengthen manufacturing, agricultural processing, mineral development and other value-adding sectors to drive economic diversification and competitiveness.
He identified reliable electricity supply, efficient transportation and logistics systems, affordable financing and predictable regulation as critical enablers for businesses to thrive and compete effectively.
In essence, he said, a tax policy that encourages investment must be supported by an economic environment where such investments can yield returns.
He also highlighted the complementary roles of technology, insurance, trade and the capital market in building a resilient economy.
According to him, digital financial services can lower transaction costs, broaden financial inclusion and enhance efficiency in tax administration, while insurance helps to protect businesses and households against risks, safeguard productive assets and mobilise long-term funds for investment.
He added that trade facilitation and export development remain vital for enabling Nigerian businesses to access larger markets across Africa and beyond.
Mr. Oyedele described these sectors as interconnected pillars of economic growth, where investment drives production, production creates jobs, employment raises incomes, technology improves efficiency, insurance protects assets and trade provides access to new markets.
He noted that for Nigeria to achieve its one trillion dollar economy ambition, the relationship between fiscal policy, technology, insurance, trade and the capital market must translate into measurable gains in productivity, stronger businesses and broader economic opportunities for citizens.
The capital market, he said, remains critical in mobilising long-term funds for businesses, infrastructure development and other productive activities that drive growth.
Mr. Oyedele also spoke on the responsibility of the media in shaping public understanding of economic reforms.
He called on members of the Finance and Business Online Publishers Association, FiBOP, and the wider media community to help Nigerians understand the objectives and implications of ongoing economic reforms.
He urged journalists and online publishers to distinguish between verified economic data and speculation, and to clearly differentiate between proposed policies and those already under implementation.
According to him, accurate and responsible reporting is essential to prevent misinformation and to build public confidence in the reform process.
However, he also placed responsibility on the government to provide timely and transparent information, explain the rationale behind its decisions and welcome constructive scrutiny from the public and the media.
Public confidence, he said, is strengthened when citizens understand not only what government is doing, but why it matters and how progress will be measured.
His remarks underscored the importance of public trust as a critical factor in the successful implementation of economic reforms, especially where such policies directly affect businesses, investors and households.
Mr. Oyedele stated that ultimately, Nigeria’s one trillion dollar economy ambition will require more than policy pronouncements and revenue projections.
He said it will depend on sustained investment, robust infrastructure development, improved access to finance, growth of productive enterprises and consistency in government policies.
For him, the real measure of success will be whether the reforms improve productivity, create jobs, strengthen businesses and raise the living standards of Nigerians.
He noted that the challenge before government is to ensure that economic growth translates into shared prosperity and tangible benefits for the population.
If the new tax policy succeeds in encouraging investment and expanding productive activities without imposing unnecessary burdens on ordinary citizens and businesses, he said, it could become a vital instrument in Nigeria’s journey towards achieving a one trillion dollar economy by 2030.